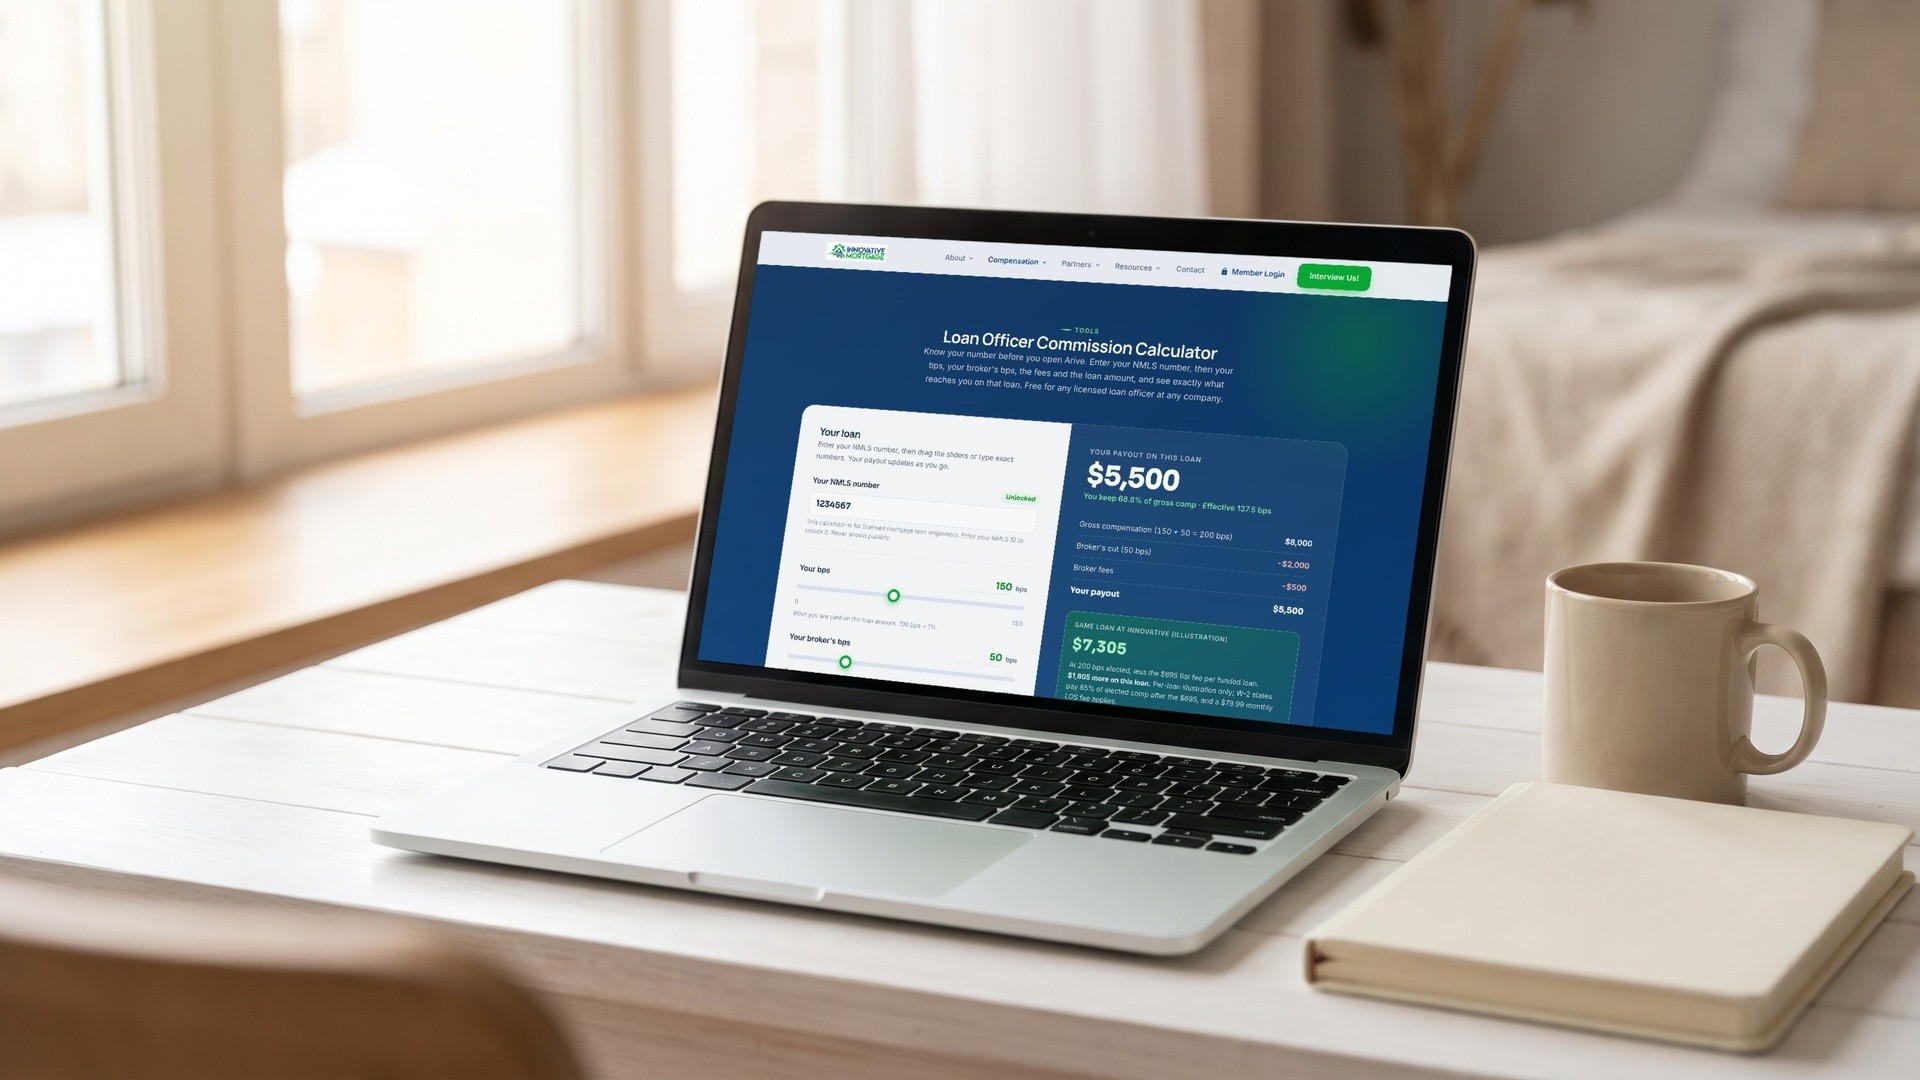
Loan officer commission is calculated in basis points of the loan amount. Add your bps and your broker's bps to get gross compensation, apply it to the loan amount, then subtract the broker's cut and any per-loan fees. What's left is your payout. The free loan officer commission calculator runs that math in one place for any licensed loan officer at any company. Enter your NMLS ID to unlock it, and you'll know your payout on a loan before you build the file.
MLOs, most of you know your own bps. The number worth checking on every scenario is what reaches you once the broker's share and the fees come out of the gross.
The formula
Gross compensation = Loan amount × (Your bps + Broker's bps)
Broker's cut = Loan amount × Broker's bps
Your payout = Gross compensation − Broker's cut − Per-loan fees
Three inputs come from your plan and rarely change: your bps, your broker's bps, and any per-loan fees. One input changes on every file: the loan amount. That's why the calculator remembers the first three on your device and lets you change the last one in seconds.
A worked example, step by step
Take a $400,000 loan with 150 bps for you, 50 bps for your broker (200 bps gross) and a $500 processing fee.
- Gross compensation: $400,000 × (150 + 50) bps = $8,000
- Broker's cut: $400,000 × 50 bps = $2,000
- Per-loan fees: $500
- Your payout: $8,000 − $2,000 − $500 = $5,500
That $5,500 is 68.75% of the gross compensation. As a share of the loan, that's 137.5 bps: the effective bps you keep. Effective bps is the number to compare across companies, because two loans can both pay 200 bps gross and leave you very different amounts once the broker's share and the fees come out.
Converting bps to dollars
One basis point is one hundredth of one percent, so 100 bps is 1% of the loan amount. On a $300,000 loan, each basis point is worth $30.
| Gross bps | As a % | $200,000 loan | $400,000 loan | $700,000 loan |
|---|---|---|---|---|
| 100 bps | 1.00% | $2,000 | $4,000 | $7,000 |
| 150 bps | 1.50% | $3,000 | $6,000 | $10,500 |
| 200 bps | 2.00% | $4,000 | $8,000 | $14,000 |
| 275 bps | 2.75% | $5,500 | $11,000 | $19,250 |
These are gross figures, before the broker's cut or any fee. For more on the unit itself, see 275 basis points: the truth about loan officer pay.
If your company quotes a percentage split
Turn the split into bps before you enter it. Multiply the gross bps by the company's percentage. On a 70/30 split of 200 bps gross, the company keeps 200 × 0.30 = 60 bps and you get 140. Enter 140 as your bps and 60 as your broker's bps.
On the same $400,000 loan with no per-loan fee, that's $8,000 gross, a $2,400 broker's cut, and a $5,600 payout, or 140 effective bps.
Flat fee vs. a cut in bps
A cut in bps grows with the loan. A flat fee doesn't, so it takes a bigger share of a small loan and a smaller share of a large one.
At Innovative the fee is $695 per funded loan at any loan size. On a $200,000 loan at 275 bps ($5,500 of comp), the $695 is 12.6% of compensation and the payout is $4,805. On a $400,000 loan at 275 bps it's 6.3%, and on a $900,000 loan ($24,750 of comp) it's 2.8%. How the $695 flat fee works lays the same math out across more loan sizes.
What the side panel shows
Once the calculator is unlocked and filled in, the results panel also shows the same loan under Innovative's plan, labeled as an illustration. It uses the gross bps on the loan, capped at 275 (the top of the range you can elect here), less the $695.
On the worked example above, that's $400,000 × 200 bps = $8,000, less $695, or $7,305 on that loan. It's per-loan arithmetic only, so you can see both numbers side by side. The plan details, including the team plan, are on the compensation page.
What the calculator leaves out
Keep these in mind when you read your result:
- Taxes, benefits and W-2 withholding. Some states require W-2 pay for loan officers. At Innovative, loan officers in W-2 states receive 85% of elected compensation after the $695.
- Monthly fees that aren't tied to a loan. Innovative charges a $79.99 monthly LOS fee, for example.
- Lender credits, cures or concessions that come out of compensation on a specific file.
- The rules on how you can be paid. Under the federal loan originator compensation rule in Regulation Z, loan officer pay can't be based on a loan's terms, such as its rate.
Make it a habit
Bookmark the loan officer commission calculator (Ctrl + D on Windows, Cmd + D on a Mac). Your NMLS ID, your bps, your broker's bps and your fees reload on that device next time, so each new scenario is one field: the loan amount. Your NMLS ID is never shown publicly.
If you'd like to see a month of closings rather than a single loan, the Pay Raise Calculator handles that view. If you're comparing plans and want to know what keeping your commission looks like here, start with the Interview Us questionnaire.
FAQ
How is loan officer commission calculated?
Add your bps and your broker's bps to get gross compensation, apply it to the loan amount, then subtract the broker's cut and any per-loan fees. On a $400,000 loan at 150 + 50 bps with a $500 fee, gross is $8,000 and the payout is $5,500.
What does bps mean in loan officer pay?
A basis point is one hundredth of one percent. 100 bps is 1% of the loan amount, and 275 bps is 2.75%.
How do I convert a commission split to bps?
Multiply the gross bps by the company's share. A 30% company share of 200 bps gross is 60 bps for the broker and 140 for you.
What is effective bps?
Your payout as a share of the loan amount, in basis points. It's the share of the loan that actually reaches you after the broker's cut and the fees, and it's the cleanest way to compare two plans.
Why does the calculator ask for my NMLS ID?
It's built for licensed mortgage loan originators, and your NMLS ID unlocks it. It's never shown publicly or placed in a URL.
Does the calculator work if I'm not at Innovative?
Yes. It works for any licensed loan officer at any company, broker or retail. The Innovative panel is a labeled illustration beside your own result.
Does the calculator show annual income?
No. It shows the math on a single loan. Your actual pay depends on the loans you close, your agreement with your company, and state law.
Innovative Mortgage Services, Inc. NMLS ID # 250769 (https://nmlsconsumeraccess.org/)